How does a motorcycle loan work in the Philippines?
Reviewed . General information, not legal or financial advice.
Most new motorcycles in the Philippines are sold on installment. That makes the monthly amount look easy, but the total you pay can be far higher than the SRP. This guide is for first-time buyers comparing a bank, a financing company and a casa or shop like Motortrade. It explains how each route prices the loan, what papers you need, and what happens if you fall behind. Rates and listings were checked in November 2026.
What are your options for a motorcycle loan?
There are three routes, and they differ mainly in speed, paperwork and cost.
| Route | Examples | Downpayment | Terms | Published rate |
|---|---|---|---|---|
| Bank motorcycle loan | BPI Motorcycle Loan (bikes below 250cc) | From 5% on selected units | 12, 24, 36 months | 2.43% to 2.88% add-on a month |
| Bank big-bike loan | BPI Big Bike, Security Bank (400cc and up) | 30% | 12 to 36 months | 26.05% to 27.84% total add-on for 36 months |
| Financing company | Salmon Moto Loan, Home Credit, Cebuana Cycle Financing | Salmon: 10% (5% for existing clients) | Salmon: 12, 18, 24, 36 months | Not published |
| Dealer in-house | Motortrade and similar shops (financed by partner lenders) | Fixed peso amount per unit | Calculator offers 12 to 36 months | Not published |
Bank motorcycle loans
BPI is the main bank with a published rate for everyday bikes. Its Motorcycle Loan covers brand-new and second-hand units below 250cc, lends up to ₱400,000, and is offered through partner dealers such as Premiumbikes and Summit Superbikes as well as BPI branches. See BPI financing for how it compares with the bank's car loans.
Big bikes are a different product. BPI's Big Bike loan needs a unit of at least ₱200,000 and finances up to 70%, while Security Bank's applies to 400cc and up with a minimum SRP of ₱300,000. Their rates are much lower per month than regular-bike rates, which is why the bank chart below can look cheaper than what a scooter buyer will actually be quoted.
Financing companies
Salmon offers a Moto Loan of up to ₱200,000 for brands including Honda, Yamaha, Kawasaki and Suzuki. You apply through an offer in its app, its online Moto Marketplace (Greater Manila and nearby provinces), or a QR code at a partner store. Details are on the Salmon financing page.
Home Credit works through partner stores, which it puts at more than 500 nationwide, including Emcor and KServico. It asks for one primary ID with address, plus proof of income for new clients. Cebuana Lhuillier entered motorcycle financing in 2025 through Cebuana Cycle Financing Inc., a joint venture with GDFI Holdings. Neither publishes a rate or a standard downpayment, so get a written quote.
Dealer in-house financing
In-house means you apply at the shop and the shop arranges the loan, often with a partner lender. Motortrade, for example, lists Bank of Makati, Fundline Finance and Northpoint Development Bank as partners, and its FAQ says the CI is done by a Bank of Makati or Fundline investigator. The appeal is convenience: one counter, low cash-out, and same-day release once you pass.
Why are in-house monthly payments higher?
Because most motorcycle installments use an add-on rate. The lender charges interest on the full amount financed for the whole term, even though you pay the balance down every month. A rate that sounds small per month becomes large over 36 months.
Take BPI's lower published rate of 2.43% a month. Over 36 months that is 87.48% of the amount financed. Because you repay principal as you go, the true cost works out to about 46.7% a year as an effective rate. Read add-on rate versus effective rate for the full explanation.
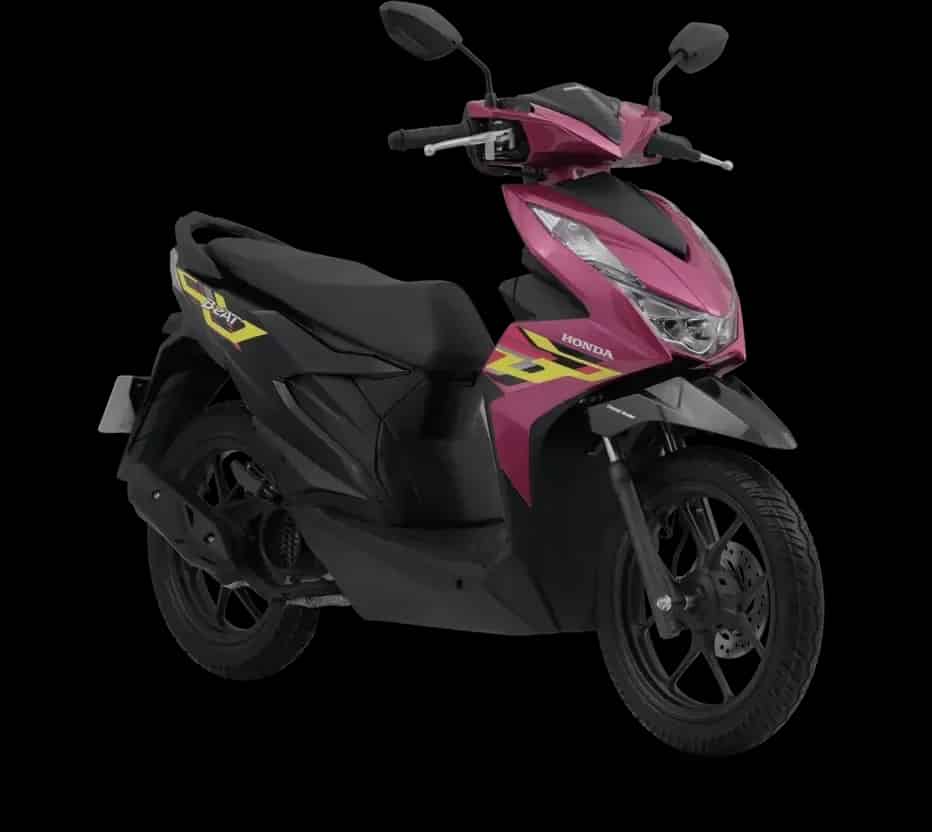
Dealer listings often show only the downpayment and the monthly, not the number of months. When we checked Motortrade's home page in November 2026, a Honda BeAT Premium with an SRP of ₱74,900 was listed at ₱2,000 down and ₱3,400 a month. That is ₱83,600 in total over 24 months but ₱124,400 over 36. The term changes the total by more than ₱40,000, so always ask for it.
Total add-on rate over the whole term, as published by each lender (latest check 13 November 2026). Lower is cheaper. Rates change and depend on your profile; see the calculator for your numbers.
The chart shows published total add-on rates for 36 months. Big-bike products sit far below BPI's regular-bike rate, so use the regular-bike figure when you are pricing a scooter or underbone.
A DTI order (Department Administrative Order 21-03, 2021) bans installment-only selling. Dealers must accept cash, installment or a mix, post the options visibly, and may give a cash discount. If a shop refuses your cash, you can report it to the DTI.
How much does a ₱120,000 motorcycle cost on installment?
With 20% down and 36 months at BPI's lowest published regular-bike rate, a ₱120,000 motorcycle costs about ₱204,000 in total.
| Item | Amount |
|---|---|
| Price | ₱120,000 |
| Downpayment (20%) | ₱24,000 |
| Amount financed | ₱96,000 |
| Add-on interest, 2.43% x 36 months (87.48%) | ₱83,981 |
| Monthly installment | ₱4,999 |
| Total paid (down plus 36 monthlies) | ₱203,981 |
At the top of BPI's range, 2.88% a month, the monthly rises to ₱5,431 and the total to about ₱219,500. These figures exclude registration, insurance and any fees the lender adds. A shorter term cuts the total sharply, which the chart below shows using the median published motorcycle rate.
| Term | Monthly | Total interest |
|---|---|---|
| 12 months | ₱10,333 | ₱27,996 |
| 24 months | ₱6,333 | ₱55,992 |
| 36 months | ₱5,000 | ₱84,000 |
Average of the total add-on rates published by the lenders we track for each term (1 or more lenders). Estimates, not offers; fees such as chattel mortgage and insurance are extra.
The chart uses only loans a regular 125cc bike qualifies for, which in our data means bank rates; financing companies and in-house plans usually cost more, so treat it as a best case. Plug your own quote into the calculator:
Try it: motorcycle loan calculator
- Amount financed
- ₱72,000
- Total interest
- ₱63,000
- Total cost (down payment, instalments and fees)
- ₱153,000
- Cash needed up front
- ₱18,000
- Add-on rate for the term
- 87.48%
Estimate only, not a loan offer. Rate source: Average of Bank of the Philippine Islands (BPI), verified 13 November 2026. Insurance, registration and chattel mortgage fees are extra unless stated.
The full version is on the motorcycle loan calculator page.
What are the requirements for a motorcycle loan?
Most lenders ask for valid IDs, proof of income and proof of address. The specifics vary by lender and by how you earn.
| Document | BPI Motorsiklo Loan | Salmon | Home Credit | Motortrade |
|---|---|---|---|---|
| Valid ID | 1 BSP-accepted ID with signature | 2 valid IDs | 1 primary ID with address | 2 valid IDs |
| Proof of income (employed) | 1 month payslip or COE | Payslip, COE or ITR (recommended, not required) | COE, payslip, SSS/GSIS record, or app earnings report | COE and 1 month payslip |
| Proof of income (self-employed) | Business permit plus 3 months bank statements | Permit, bank or e-wallet statements | As above | Not stated |
| Proof of billing | Not listed | Not listed | Accepted as secondary ID | Not listed |
Bank of Makati's application guide also lists a utility bill or lease as proof of residence and two 2x2 photos. OFWs usually show their contract and three months of remittances.
Banks add eligibility rules. BPI's requirements page asks applicants to be 21 or older and no more than 60 at loan maturity (its main loan page says 18 to 65), to have lived at the same address for one year if owned or two if rented, and to have one year of regular employment or two years in business. It also requires no derogatory credit record.
A COE (Certificate of Employment) is a letter from your employer confirming your position and tenure. For loans, ask HR for one that also states your monthly salary, since BPI asks for compensation to be shown.
What does CI mean in a motorcycle loan?
CI stands for credit investigation. It is the lender's check that your identity, address, job and income match your application before it releases the unit.
In practice, CI often includes a visit to your home. Motortrade's FAQ says the CI is done at your house, scheduled around the investigator's availability and yours, and that the branch calls you with the result. Lenders may also check your record with the Credit Information Corporation (CIC), the government credit registry. You can request your own CIC report online before you apply, which helps you spot errors.
How long does approval take?
Approval ranges from minutes to several days, depending on the route.
- Home Credit at KServico stores advertises approval in as little as one minute, with one valid ID.
- Motortrade advertises same-day approval and says the unit can be released the same day once you pass CI.
- Salmon says its standard review takes 1 to 3 days, followed by an inspection at a dealer center.
- BPI and Bank of Makati do not publish a timeline; Bank of Makati says approval is sent by SMS, email or call.
Registration is separate from approval. Read LTO registration for a new vehicle for when your plate and OR/CR are due.
What happens if you miss payments?
Late payments trigger penalty fees under your contract, then collection calls, and eventually repossession. The motorcycle is the lender's security under a chattel mortgage until you finish paying.
The same part of the Civil Code allows a contract to say that installments already paid are not refunded, as long as that is not unconscionable. So a repossession can cost you both the bike and everything you paid.
Financing and lending companies are also bound by SEC Memorandum Circular No. 18 (2019), which bans unfair debt collection, including threats, insults and contacting people on your phone contacts who are not your co-makers or guarantors. If you know you will miss a payment, call the lender first. Salmon, for example, says customers may request a payment holiday, subject to approval.
How to choose
- Get the cash price first, then ask each lender for the downpayment, number of months, monthly amount and total payable in writing.
- Compare totals, not monthlies. Divide the interest by the amount financed and by the months to get the monthly add-on rate.
- Ask what is included: registration, insurance, chattel mortgage fee, and any processing fee.
- Check for brand 0% or low-rate promos on the promos page, especially for big bikes.
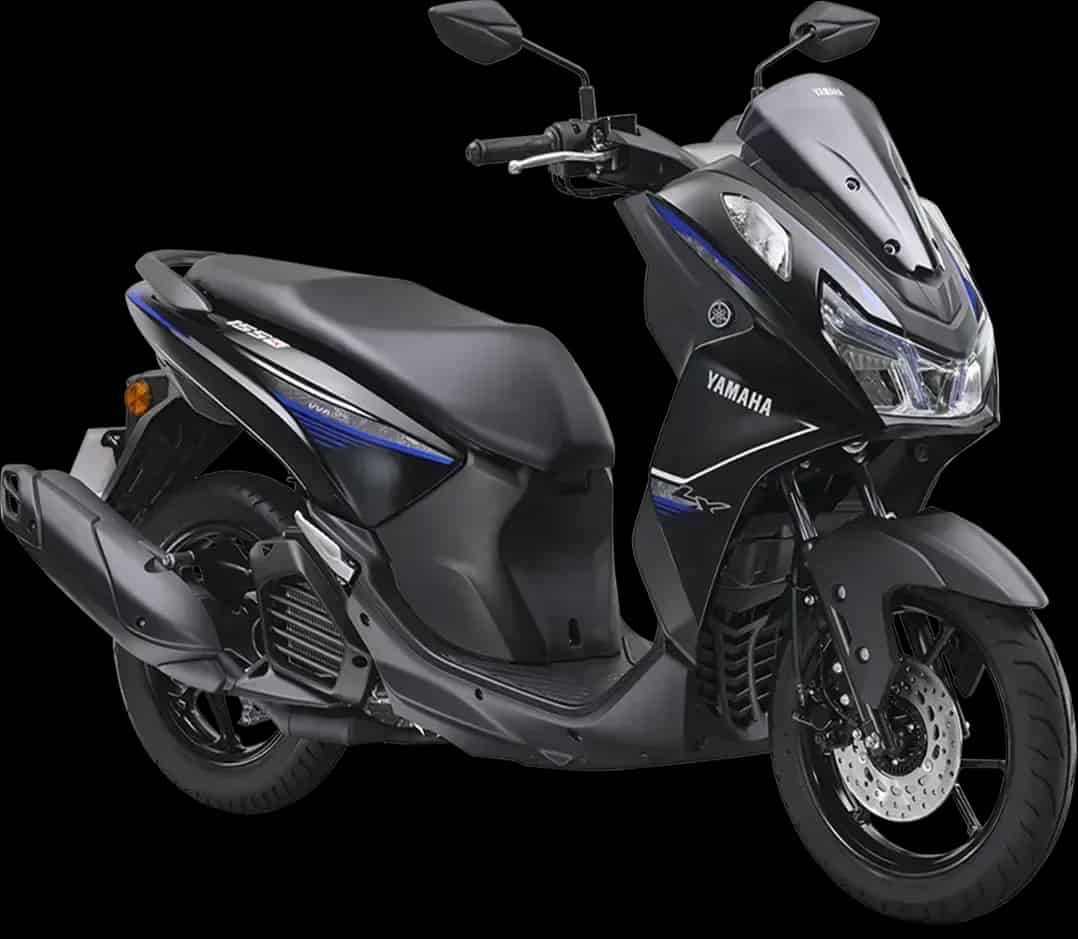
Ready to shortlist? Browse scooters or units under ₱100,000. These are the most popular scooters in that range:
Questions and answers
What is the lowest interest motorcycle loan in the Philippines?
The lowest published bank rates are for big bikes: BPI lists 27.84% total add-on over 36 months (16.72% effective a year) and Security Bank 26.05%. For regular bikes under 250cc, BPI publishes 2.43% to 2.88% a month. Brand 0% promos, when available, beat all of these.
Can I get a motorcycle loan with no downpayment?
Rarely. Salmon says it has no zero-down offers and asks 10% from new customers. BPI's regular motorcycle loan starts at 5% on selected units, and only its AYALA/GG program lists no downpayment. Low-down dealer promos usually mean a bigger monthly.
What does CI mean in a motor loan?
CI is credit investigation: the lender checks that you are who you say you are, that you live where you say, and that you can pay. It usually includes a home visit or phone call and may include a check of your credit record.
Do I need a COE for a motorcycle loan?
If you are employed, usually yes. BPI and Motortrade both ask for a Certificate of Employment or a recent payslip as proof of income. Self-employed buyers show a business permit or bank statements instead, and Salmon accepts e-wallet statements.
How long does motorcycle loan approval take?
It depends on the route. Salmon says its review takes 1 to 3 days, Home Credit advertises in-store approval in as little as a minute, and Motortrade says the unit can be released the same day once you pass CI. Banks do not publish a fixed timeline.
Can I sell a motorcycle that is still under loan?
Not freely. The motorcycle is mortgaged to the lender until the last payment, and lenders such as Salmon say it cannot be sold to a third party before full payment. Ask the lender about a formal assumption of balance instead.
Is a motorcycle loan calculator accurate?
It is only as accurate as the rate you type in. Most Philippine motorcycle loans use an add-on rate, so check whether the calculator wants a monthly add-on rate, a total add-on for the term, or an effective annual rate.
Sources
- BPI: Motorcycle Loan (rates, downpayment, terms, eligibility)
- BPI: Motorsiklo Loan requirements
- BPI: Auto Loan for Big Bike
- Security Bank: Motorcycle Loan (big bikes, 400cc and up)
- Salmon: What is Salmon Moto Loan?
- Home Credit Philippines: Motorcycle loan
- Top Gear Philippines: Home Credit and KServico motorcycle financing (19 May 2025)
- Philippine Star: Cebuana Lhuillier and GDFI Holdings partner on motorcycle financing (2025)
- Motortrade: Frequently asked questions
- Motortrade: home page unit listings with downpayment and monthly (read November 2026)
- Bank of Makati: How to apply for a bank motorcycle loan (5 December 2024)
- Top Gear Philippines: DTI order bans installment-only sales (27 April 2021)
- Civil Code of the Philippines, Articles 1484 to 1486 (Lawphil)
- Grant Thornton Philippines: SEC Memorandum Circular No. 18, Series of 2019, on unfair debt collection
- Credit Information Corporation: About your CIC credit report